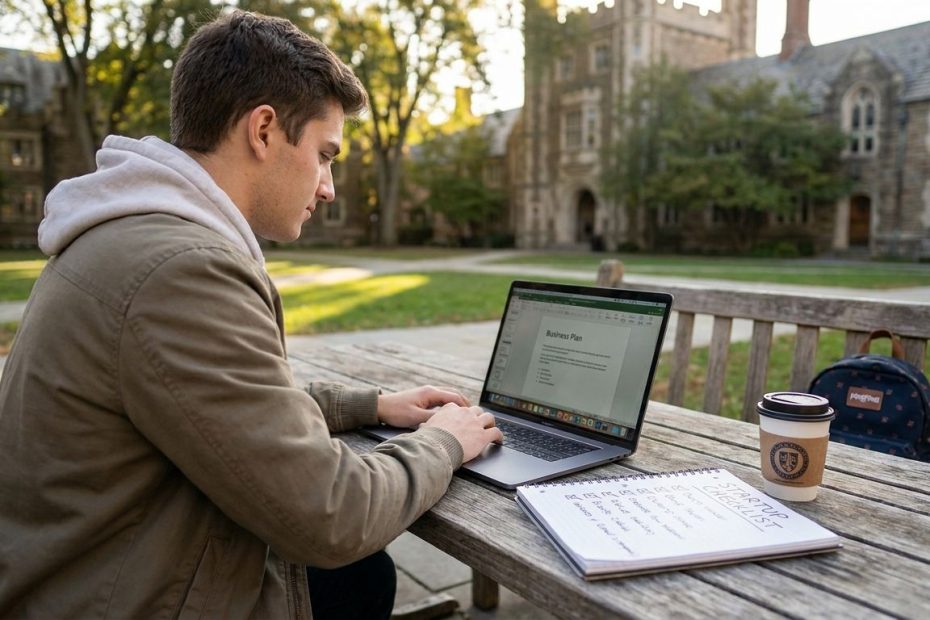
Launching your first business in college works best when you keep the sequence simple: validate demand, sell a small version fast, then handle legal, tax, banking, and campus policy details once the business shows real traction. If you build in that order, you protect your time, reduce wasted money, and give yourself a real chance to grow something that fits your class schedule instead of fighting it.
You do not need a perfect logo, a polished website, or a long business plan to get moving. You need a clear customer problem, a practical first offer, and a disciplined setup process that keeps your operation clean from day one. This guide walks you through the exact steps that matter most when you are starting a business as a college student, from idea validation to opening a business bank account and checking whether your university can claim any rights in what you build.
Step 1: Validate A Problem You Can Solve On Campus
Your first move is not filing paperwork. Your first move is proving that people will pay for a solution. The Small Business Administration places market research at the front of the startup process for a reason: if you skip it, you risk building something nobody wants.
In college, your easiest market is usually right in front of you. Student clubs, campus organizations, local restaurants near campus, student athletes, graduate students, faculty labs, and nearby small businesses all have recurring needs. Tutoring, social media content, event photography, resume support, design work, note organization, research assistance, moving help, and niche e-commerce offers can all work, but only if they solve a specific pain point that people already feel.
Start with ten to twenty short conversations. Ask what frustrates people, what they are already paying for, what they have tried, and what still feels broken. Keep your questions tight and practical. You are looking for repeated pain, not compliments about your idea. If several people describe the same problem in similar language, you have something worth testing.
Once you hear a pattern, shape a first offer around one job, one customer type, and one result. A focused offer wins faster than a broad one. “Monthly social media management for campus clubs” is stronger than “digital marketing services.” “Organic chemistry exam prep for pre-med sophomores” is stronger than “tutoring.” Precision saves time, sharpens your message, and makes pricing easier.
Step 2: Presell A Small Offer Before You Build Anything Bigger
The fastest way to test your business is to ask for money. Not a survey response, not a like, not a vague “I would use this.” A paid pilot tells you whether the problem is painful enough for someone to act. That single step can save you months of wasted effort.
Create a minimum offer that you can deliver manually within your schedule. If you want to build software, start with a manual version first. If you want to sell products, start with a preorder or a limited batch. If you want to launch a service, define a narrow package with a set price, a short timeline, and a clear outcome. Keep the scope small enough to execute between classes, assignments, and exams.
Your goal is not scale at this stage. Your goal is proof. If a student club agrees to pay you to run one event campaign, if a local café pays for ten edited short-form videos, or if a few students prepay for a focused tutoring package, you now have a signal worth trusting. Revenue, even small revenue, gives you better information than opinions.
Use that early pilot to measure four things: how many people showed real interest, how many paid, how much work delivery required, and whether anyone wanted to buy again. Those numbers help you decide whether to keep going, raise prices, narrow your audience, or change the offer. College founders who win early tend to keep the feedback loop short.
\Step 3: Build A Lean Business Plan That Fits Your Academic Schedule
You do not need a long formal plan to start, but you do need a working plan. The Small Business Administration recommends building a business plan early, and for a college founder the smartest version is lean, short, and operational. You want a plan you will actually use every week, not a document that sits untouched in a folder.
Your lean plan should answer a few direct questions. Who exactly is the customer. What exact problem are you solving. What is your first offer. How will people hear about it. What will you charge. What will it cost to deliver. How many hours can you realistically commit each week without damaging your grades or your health. If you cannot answer those questions in plain language, you are not ready to scale.
Set capacity limits early. Your class schedule is not a minor detail; it is part of your operating model. If you can only serve five tutoring clients a week or edit eight videos a month, build your pricing and delivery around that ceiling. College businesses often break not because demand is weak, but because the founder oversells and cannot deliver consistently.
Include a simple monthly target. One revenue goal, one customer acquisition goal, and one retention goal are enough to start. That discipline keeps your business measurable. It also helps you decide what to ignore, which matters when campus life throws new distractions at you every week.
Step 4: Decide Whether To Start As A Sole Proprietor Or Form A Limited Liability Company
This is where many student founders get stuck. They assume they need a Limited Liability Company, also called an LLC, before they can sell anything. In many cases, that is not true. If you are starting a simple low-risk service business by yourself, you can often begin as a sole proprietor and formalize later when the business grows, risk increases, or you add partners.
A sole proprietorship is the simplest path. It has minimal startup friction, fewer administrative steps, and lets you test demand without overbuilding your back office. That makes it attractive for student freelancers, tutors, designers, photographers, and other service-based founders. The tradeoff is that there is less legal separation between you and the business.
An LLC becomes more useful when you want stronger separation, shared ownership, contract credibility, or protection suited to a business with more exposure. If you plan to sell physical products, run events, hire people, sign bigger client contracts, or operate with business partners, the LLC conversation becomes more important. Your state rules matter, and your risk level matters even more.
The Internal Revenue Service makes one point especially clear: if you are creating an LLC, partnership, or corporation, register the entity with your state before applying for an Employer Identification Number, also called an EIN. Many beginners confuse state formation with federal tax identification. They are separate steps, and mixing up the order creates avoidable delays.
Step 5: Get Your Employer Identification Number The Right Way
Your Employer Identification Number is your business tax identification number, and the Internal Revenue Service states that getting one is free. You do not need to pay a third-party service for it. That matters because new founders often end up on lookalike websites that charge fees for something the government provides at no cost.
If you stay a sole proprietor, you may not always need an EIN immediately for every situation, but many founders still get one to separate business activity from personal tax identifiers when opening accounts or working with vendors. If you formed an LLC or another entity type, the EIN usually becomes part of your standard setup sequence right away. The Internal Revenue Service notes that the online application can be completed quickly when you have your information ready.
Before you apply, make sure your legal structure is decided. If you formed an LLC, complete the state registration first. Then go directly to the official Internal Revenue Service process, enter the entity details accurately, and save your confirmation documents the moment you receive them. Keep digital copies and printed copies. Banks and payment processors may ask for them later.
This is one of those steps where organization saves you hours. Create one folder for formation documents, tax records, account confirmations, contracts, and receipts. If you build that habit now, you make banking, bookkeeping, and tax filing far easier when your semester gets busy.
Step 6: Open A Business Bank Account And Keep Your Money Separate
Once you start collecting money, separation matters. Mixing business income with your personal spending is one of the fastest ways to create confusion. It makes taxes messier, bookkeeping less reliable, and financial decision-making weaker. If you want to operate like a real business, open a dedicated business account as soon as your setup supports it.
Requirements vary by bank, but you will generally need identification, formation documents if you created an entity, and your Employer Identification Number documentation. Stripe’s business banking guidance reflects a common reality for founders: once you are incorporated or have the tax identification needed for your setup path, you can move into banking and payment infrastructure. The exact bank requirements differ, so verify before applying.
Use that account for every business transaction. All customer payments should land there. All business expenses should leave from there. Do not pay for textbooks, food, rent, and entertainment out of the same account you use for client deposits and software subscriptions. Clean separation gives you accurate numbers, and accurate numbers give you control.
From day one, track revenue, direct costs, software tools, travel, supplies, and subscriptions. Save receipts. Label transactions. Even a simple spreadsheet works at the beginning if you keep it current. Students often think bookkeeping can wait until tax season. It cannot. If you delay recordkeeping, the mess compounds fast.
Step 7: Set Up Payments, Pricing, And Simple Operating Rules
Getting paid should be easy for your customer and easy for you to reconcile. Once your banking setup is in place, connect a payment method that fits your offer. Service businesses may use invoices, card payments, or bank transfers. Product businesses may use an e-commerce checkout. The important part is consistency between your business name, tax details, and bank details so payment processors do not freeze funds over mismatched information.
Your pricing needs to reflect more than what feels fair. It needs to reflect your available time, the effort required, and the value of the result. A college founder often underprices out of fear, then burns out because the workload does not match the pay. Start with a simple package structure. Define what is included, what is excluded, how long delivery takes, how revisions work, and when payment is due.
Set operating rules early. Use written agreements, even for small projects. Confirm the deliverables, deadlines, payment schedule, and communication channel in writing. That level of clarity reduces disputes and protects your schedule. If you let every client define the process, your business becomes reactive and hard to manage during the semester.
It also helps to build one repeatable workflow. Lead comes in, discovery conversation happens, scope is defined, payment is collected, work is delivered, testimonial is requested, referral is invited. Repeatable systems reduce mental load, and lower mental load is a major advantage when you are balancing coursework and business execution.
Step 8: Use Free Mentoring And Startup Resources Instead Of Figuring Everything Out Alone
One of the smartest moves you can make is getting advice from people who have already seen early-stage mistakes up close. SCORE offers free business mentoring and workshops, and it is backed as a Small Business Administration resource partner. That gives you access to experienced guidance without adding cost to your startup budget.
You do not need a polished company to benefit from mentoring. Bring your offer, your target customer, your pricing draft, and your questions. Ask for feedback on sales, margins, customer acquisition, and workload. A good mentor can spot weak assumptions faster than you can spot them alone, especially when you are close to the idea and short on time.
If your startup comes out of technical research or university innovation work, the National Science Foundation’s Innovation Corps, known as I-Corps, can also be relevant. That path is especially useful if you are building something tied to science, engineering, or research commercialization. It trains founders to test market demand rather than assuming technical novelty creates demand by itself.
You should also look on campus. Entrepreneurship centers, startup clubs, pitch competitions, alumni networks, incubators, and professor referrals can all accelerate your progress. The strongest college founders use the campus as a platform, not just a place where they happen to live while building.
Step 9: Check Your University’s Intellectual Property Rules Before You Scale
If your business involves technology, research, inventions, code, product design, or anything built with university equipment or faculty involvement, you need to read your university’s intellectual property policy early. This is not a minor legal footnote. It can affect ownership, licensing rights, and your ability to commercialize what you created.
University policies differ. Some schools give students strong ownership rights for student-initiated work. Others may claim rights if the work used significant university resources, came out of sponsored research, or included faculty or staff as inventors. The examples in university policies and state regulations show that the details can shift meaningfully from one institution to another.
Your safest move is to identify the exact policy that governs student-created inventions, software, research output, and startup projects at your school. Read the definitions. Pay attention to phrases about significant use of facilities, course assignments, grant-funded work, lab access, and joint inventorship. If anything is unclear, contact the university office that handles technology transfer, innovation, or commercialization before your startup gets deeper into development.
This matters even more if you are building with classmates, graduate researchers, or professors. Ownership confusion can stay hidden early and explode later when a product gets traction. Clarity at the beginning protects your time, your relationships, and the business you are trying to launch.
Step 10: Launch Small, Measure Weekly, And Expand Only After The Model Works
Your first launch should be small enough to manage and clear enough to measure. You are not trying to impress everyone on campus. You are trying to prove that one customer segment will buy one offer at a profitable price and come back for more. That is the operating standard that matters.
Pick a short launch window and a narrow channel. That might mean direct outreach to student organizations, referrals from one department, partnerships with local student housing groups, or targeted messages to a campus community. Keep the campaign focused so you can tell what actually drove interest. If you promote everywhere at once, you learn very little.
Every week, review a short scorecard. How many people did you contact. How many replied. How many discovery calls happened. How many paid. What was the average project value. How many hours did delivery require. Did any customer refer someone else. Those numbers tell you whether to raise prices, improve your sales message, narrow your niche, or streamline fulfillment.
Do not expand into new offers too early. One of the most common student-founder mistakes is adding services, products, and side ideas before the first model is stable. Keep the business focused until revenue is predictable, delivery is clean, and your academic schedule can handle the workload. Scale after the engine works, not before.
What Mistakes Should You Avoid When Starting A Business In College?
The biggest mistake is building before selling. Students often spend weeks on branding, websites, names, and legal setup before they know whether anyone will pay. That sequence burns momentum and drains attention. Demand comes first, then structure follows.
Another common mistake is choosing a business model that fights your schedule. If your offer requires constant availability, urgent turnaround, or long delivery hours during exam periods, your business will strain fast. Pick something you can fulfill with consistency, not just energy. Discipline matters more than excitement.
You also need to avoid weak financial habits. Co-mingled funds, missing receipts, vague pricing, and unwritten client agreements create preventable problems. They make you look less professional and reduce your ability to make decisions with real numbers.
One more issue stands out for college founders: ignoring campus rules. If your business touches research, inventions, code, equipment, lab work, or faculty collaboration, read the policy before assuming ownership is yours alone. That check takes little time and can prevent major setbacks later.
How Do You Start A Business In College The Smart Way?
- Validate a real problem with 10 to 20 customer conversations.
- Sell a small paid pilot before building more.
- Choose the right structure, sole proprietor or Limited Liability Company.
- Get your Employer Identification Number, banking, and payment setup in order.
- Track money, protect your time, and check university intellectual property rules.
Build It With Control And Give It Room To Grow
If you launch your first college business with discipline, you give yourself more than a side income stream. You build sales skill, operating discipline, customer judgment, and decision-making speed that will keep paying you long after graduation. Start with demand, not decoration. Keep the first offer tight, formalize the business when the timing makes sense, and protect yourself by getting the legal, tax, banking, and campus details right. When your numbers show traction, expand with intent instead of chasing every idea at once. That is how you turn a student startup into a business with staying power.
References:
- https://www.sba.gov/business-guide/10-steps-start-your-business
- https://www.irs.gov/businesses/employer-identification-number
- https://docs.stripe.com/atlas/payments-business-bank
- https://www.score.org/
- https://www.sba.gov/local-assistance/resource-partners/score-business-mentoring
- https://www.nsf.gov/funding/initiatives/i-corps
- https://otm.uic.edu/uic-community/ownership-guidelines/student-ownership/
- https://studentmanual.uchicago.edu/university-policies/inventions-and-discoveries/
- https://www.law.cornell.edu/regulations/ohio/Ohio-Admin-Code-3349-20-50

Mark R Graham is a private equity executive and co-founder of Drake, Goodwin & Graham, with over 20 years of experience in alternative assets and M&A. A former Vice President at Morgan Stanley and practicing attorney, he now focuses on strategic investments and educational philanthropy.